In real estate investment and advisory work, a feasibility study can be treated as a preliminary checkbox before the financial analysis begins. In practice, early decisions about buildable area, density, timing, and program mix are already shaping the investment. They determine what the financial model will have to support.
Real estate financial feasibility evaluates whether a proposed development can cover its costs, secure the required funding, and meet its financial objectives under stated assumptions. It connects the physical concept with projected cash flows, capital requirements, and risk.
A layout establishes more than what might fit on a site. It creates expectations about revenue, construction cost, and when capital will be committed or recovered. Those expectations need to be tested while the team still has room to change direction.
The Cost of Early Assumptions
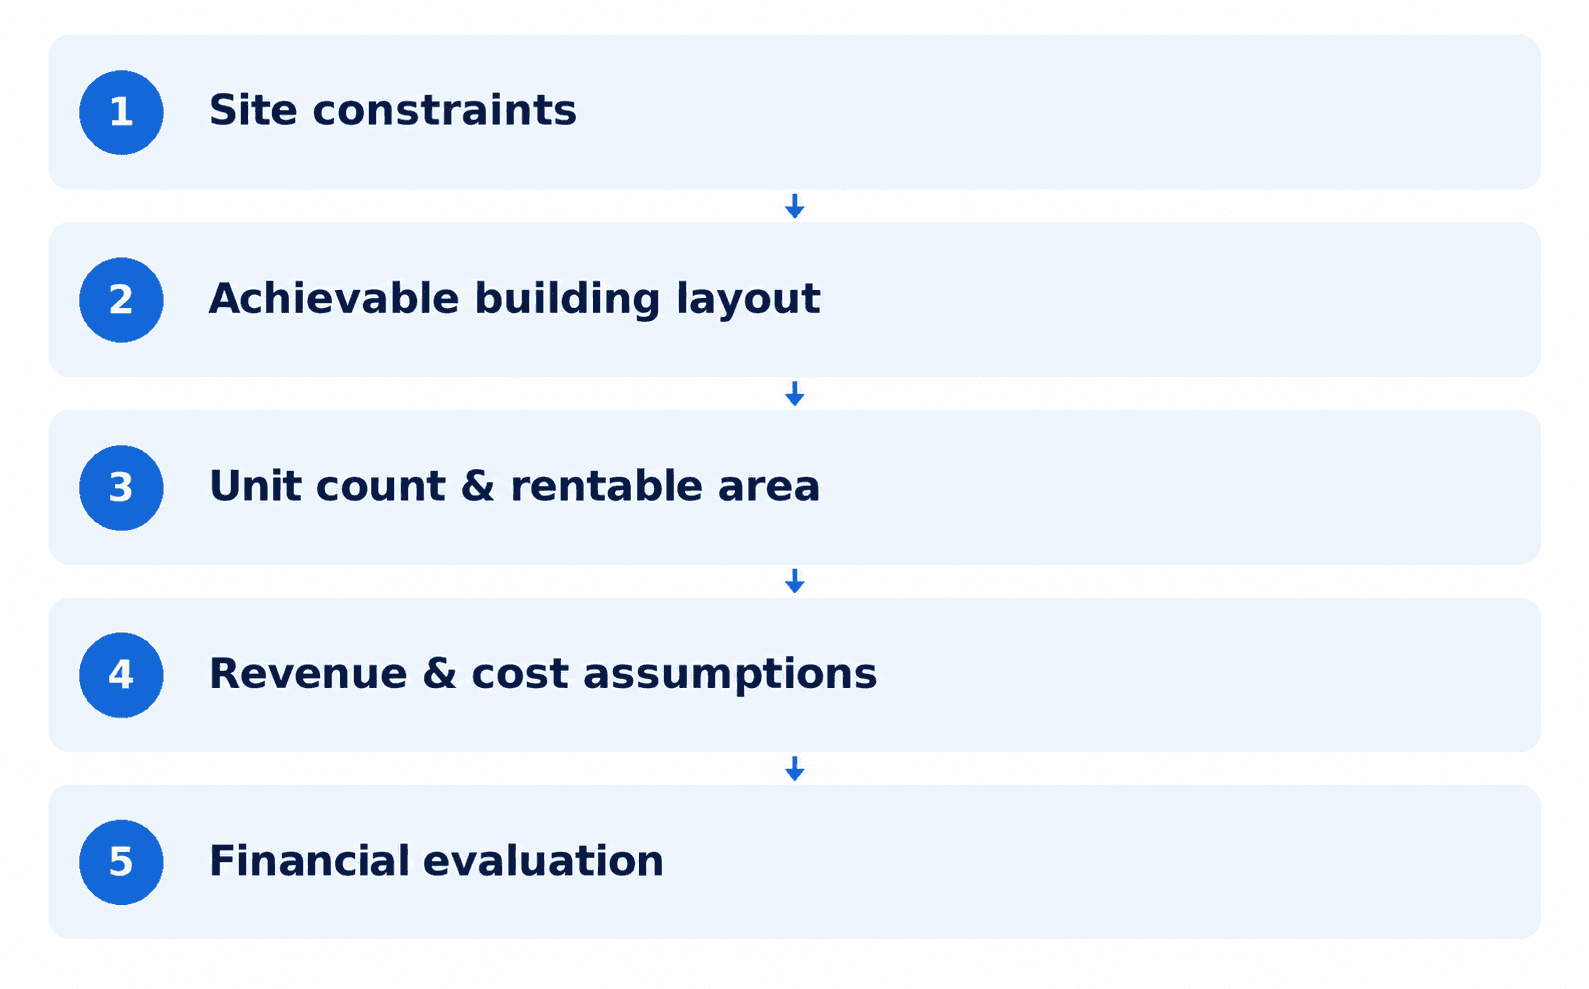
A full real estate feasibility study considers site conditions, zoning, market demand, design, and financial performance. The financial analysis brings those findings into a development pro forma: a projection of costs, funding, operating income or sales proceeds, and cash-flow timing. Financial viability does not override a physical or regulatory constraint; the conclusions need to work together.
The risk arises when a preliminary assumption becomes an accepted fact. A target unit count enters the revenue model before the parking layout is resolved. Gross building area is treated as rentable area. A preliminary construction rate remains in place after a change in building configuration. The spreadsheet may calculate correctly while describing a project the site cannot support.
This is why the source and status of each input matter. Connect rent assumptions to relevant market evidence, costs to a defined scope, and project quantities to the current concept. Track unresolved conditions separately so the team can see which conclusions depend on them.
The value of this work includes identifying sites that should not proceed. A study that supports a decision to walk away can prevent a larger commitment to an unsuitable project. Its fee alone does not establish whether the analysis was worthwhile.
Financial Feasibility Metrics: What the Inputs Become
The appropriate metrics depend on the project strategy. A rental development needs an operating forecast; a build-to-sell project needs sales prices, absorption, selling costs, and a cash-flow schedule. Each also needs a development budget and funding plan. The Housing Solutions Lab’s explanation of development pro formas connects these funding and income schedules.
Net operating income (NOI) is effective operating revenue minus operating expenses, before debt service, income tax, depreciation, and capital expenditures. State how vacancy, concessions, and reserves are treated. NOI helps describe property operations; it is not the cash distributed to equity investors.
Yield on cost is stabilized annual NOI divided by total development cost. It connects the completed project’s operating income to the cost of creating it. Include land, hard and soft costs, financing costs, and applicable contingencies in the stated cost scope.
Capitalization rate is annual NOI divided by property value, using a consistent income basis. Rearranging the equation gives an indicative value: NOI divided by an assumed cap rate. A cap rate is not the same as yield on cost, and an exit cap-rate assumption is not a guaranteed sale price.
Debt service coverage ratio (DSCR) compares income available for debt service with debt payments over the same period. A simplified screening calculation uses annual NOI divided by annual principal and interest. Apply the lender’s actual definition when underwriting: Fannie Mae’s definition, for example, uses underwritten net cash flow.
Internal rate of return (IRR) is the discount rate at which the net present value of the modeled cash flows equals zero. It captures both amounts and timing. Distinguish project-level cash flows from equity cash flows after financing, and assess IRR alongside net present value (NPV), required equity, and the assumptions behind the result. The CFA Institute discusses NPV and IRR as investment evaluation tools.
Speed as a Financial Variable
Speed in feasibility matters when it changes the timing or quality of a decision. Earlier answers may allow an acquisition team to revise its offer, investigate a constraint, or stop spending on a site. For a project already carrying debt, a shorter schedule may reduce financing expense if it actually reduces the period or amount of borrowing.
Those benefits should follow the project’s cash-flow schedule. Faster modeling does not automatically shorten an approval process, advance construction, or reduce interest. A remaining dependency may absorb the time saved. Model the milestone that changes and the expenses or receipts tied to it.
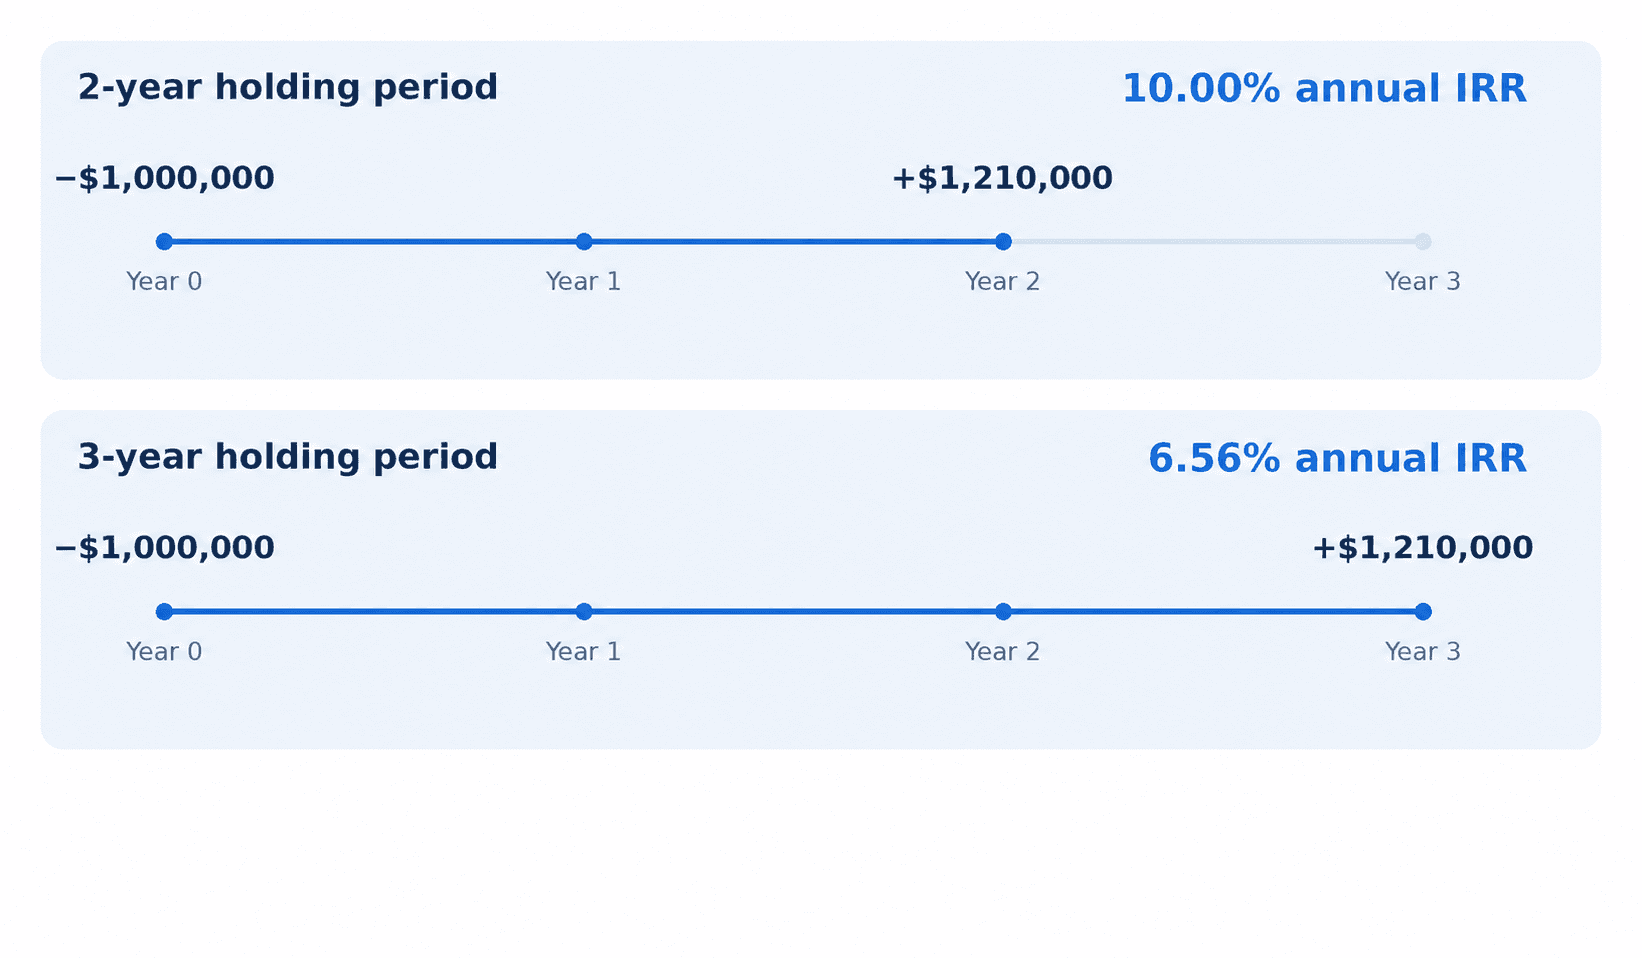
Timing also affects returns independently of the final sale price. For a simple hypothetical investment with $1 million paid at the start and $1.21 million received at the end, with no intermediate cash flows, a two-year holding period produces an annual IRR of ($1.21 million ÷ $1 million)^(1/2) − 1 = 10%. If the same receipt arrives after three years, IRR becomes (1.21)^(1/3) − 1 = approximately 6.56%. This isolates timing; a real development model must also capture any additional costs or revenue during the delay.
For the separate question of whether faster production pays for the workflow itself, see our discussion of the ROI of real-time feasibility.
Scenario Testing and Real Option Value
A single pro forma describes one path through a project. It does not explain how the decision changes if rents are lower, construction is more expensive, or the concept requires a different parking solution. Scenario testing brings those dependencies into view before commitments narrow the available choices.
Development flexibility can include phasing construction, changing the program mix, or adjusting when a later stage begins. These choices may have value, but they must be physically, legally, contractually, and financially available. The cost of preserving flexibility also matters.
Use sensitivity analysis to vary one input and understand its effect. Use a scenario to combine related changes, such as slower leasing, greater concessions, and a later stabilization date. Compare a supported base case with plausible alternatives rather than treating the most optimistic assumptions as the default.
Our Pivotal Architecture case study illustrates physical alternatives through townhome and active adult apartment/condominium concepts on the same site. Financial analysis then needs to connect each concept to its own costs, market assumptions, and timing.
A Worked Financial Feasibility Sensitivity Example
Consider a hypothetical stabilized rental development. All figures below are illustrative assumptions in US dollars, not market benchmarks, Zenerate results, or a complete investment recommendation. Assume effective annual revenue after vacancy and concessions of $600,000, annual operating expenses of $240,000, total development cost of $6 million, annual debt service of $270,000, and a 5.5% capitalization rate.
Base-case NOI = $600,000 − $240,000 = $360,000.
Yield on cost = $360,000 ÷ $6,000,000 = 6.00%.
Simplified NOI-based DSCR = $360,000 ÷ $270,000 = 1.33×.
Indicative stabilized value = $360,000 ÷ 0.055 = approximately $6,545,455.
Now reduce effective revenue by 5%, holding the other assumptions constant to isolate revenue sensitivity. Revenue becomes $600,000 × 0.95 = $570,000. NOI becomes $570,000 − $240,000 = $330,000. Yield on cost falls to $330,000 ÷ $6,000,000 = 5.50%, and simplified DSCR falls to $330,000 ÷ $270,000 = 1.22×. At the same cap rate, indicative value becomes $330,000 ÷ 0.055 = $6,000,000.
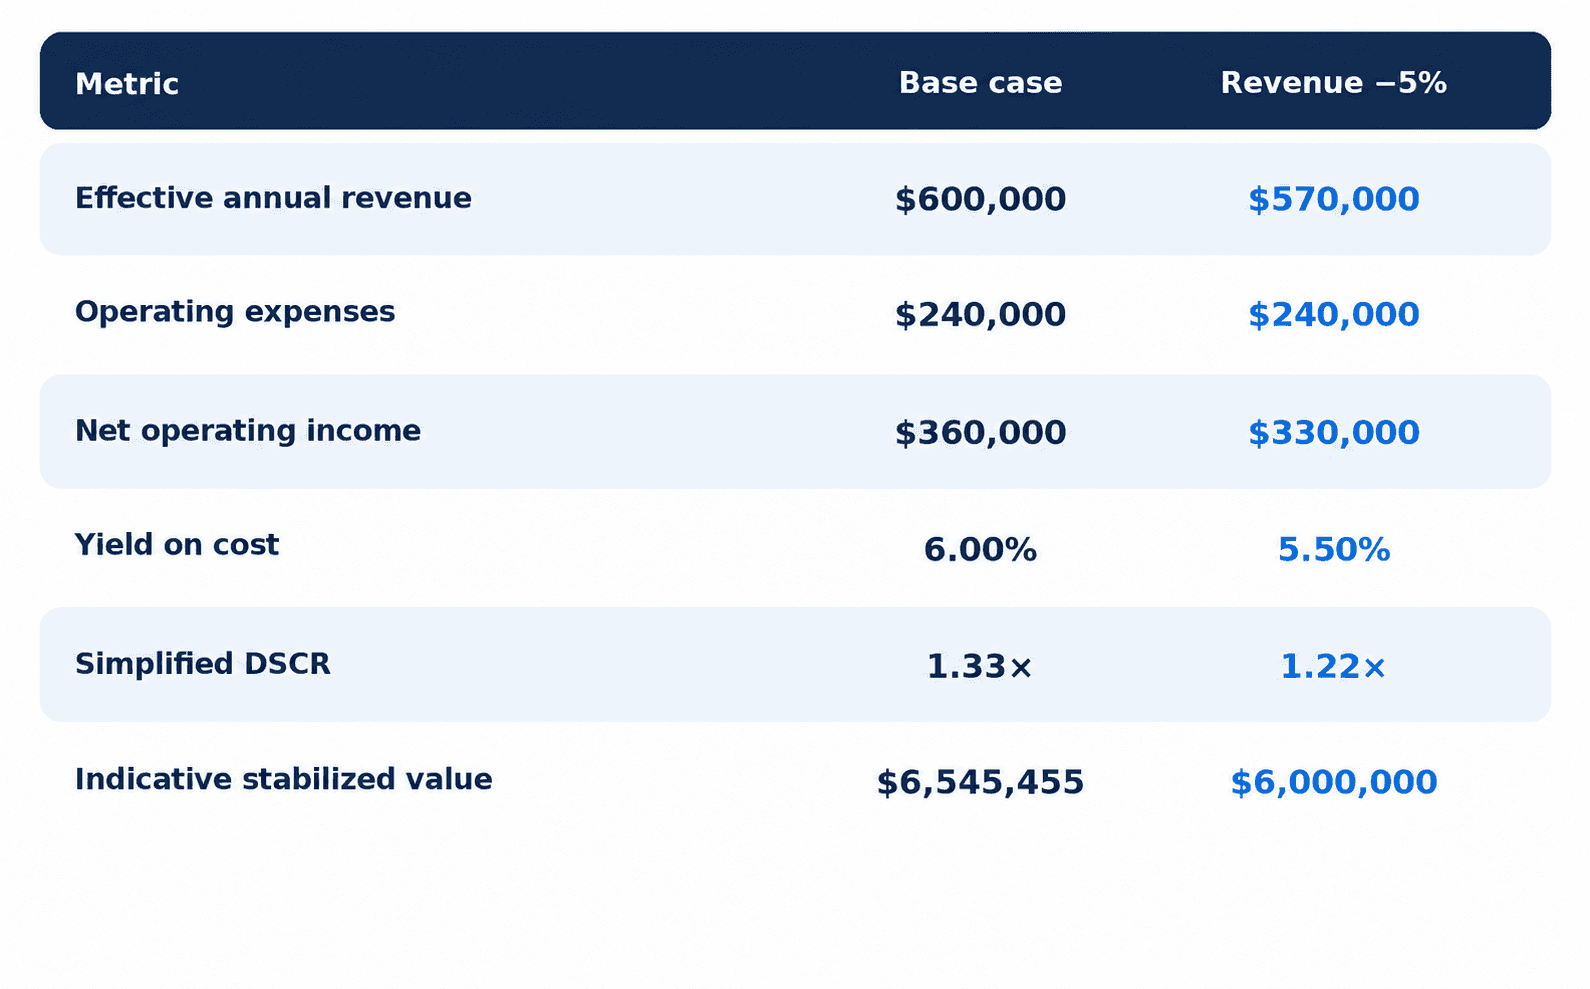
The 5% revenue reduction produces an NOI reduction of ($360,000 − $330,000) ÷ $360,000 = 8.33%, because expenses were held fixed in this sensitivity. Indicative value now equals development cost before disposition costs and any other adjustments. The example shows a thinner margin for error; it does not establish whether a lender or investor would accept the project.
A fuller model would allow relevant expenses to vary, test costs and cap rates separately, and then combine plausible downside changes. These annual figures alone cannot establish development IRR: that requires the amounts and timing of the project’s cash flows.
Aligning Technical Feasibility With Financial Reality
Design, zoning interpretation, and underwriting can develop in parallel without staying aligned. The financial model assumes one unit count while the design team is revising another. Rentable area changes, but construction cost is still based on the old gross area. The issue is the connection between inputs, not the choice of spreadsheet or software alone.
Each scenario should identify the current concept, its quantities, its assumptions, and the decision it supports. Have the design team confirm area definitions and achievable program, while the finance team reviews revenue, expenses, funding, and timing. Record changes where both teams can follow their effects.
This early alignment helps direct subsequent technical review; it does not replace engineering, environmental investigation, or entitlement work. For practical ways to manage the handoffs, see our guide to early-stage development bottlenecks.
Where Zenerate Fits Today
At Zenerate, we support the early work of turning site and design assumptions into options teams can evaluate. Our AI feasibility platform helps users generate and edit layouts, review project quantities, and explore design and financial information as the concept develops.
Your team remains responsible for interpreting applicable requirements and supplying informed assumptions. Our role is to make the design implications easier to investigate, so acquisition, advisory, and design teams can discuss alternatives before settling on a direction.
Feasibility as Risk Management
Early financial feasibility helps a team understand what must be true for a project to work. It connects the proposed design to capital requirements, identifies assumptions that deserve more evidence, and reveals where a change could alter the investment decision.
The resulting decision may be to proceed, revise the program, renegotiate the land price, investigate further, or stop. A useful study makes that choice clearer by showing both the supported case and its vulnerabilities. That is why financial analysis belongs in the feasibility discussion from the beginning.
Explore What Zenerate Can Do
If you want to connect early design exploration more closely with your feasibility analysis, book a demo with us. We can help you assess how Zenerate fits your team’s process for testing options before major capital decisions.
Book a Demo + Get a Free Trial